A gas mega-project is moving into tender. A fresh licensing round has brought new operators into the country. Mature fields are missing their production targets. All three trends are landing on procurement desks at once — and together they are reshaping oil and gas procurement in Indonesia heading into 2027.
Two storylines, one supply chain
Indonesia’s upstream sector is telling two stories at once. The first is expansion. A long-delayed LNG development is finally nearing construction, and a new licensing round has brought fresh operators into the country. The second is attrition. Mature fields are missing their 2026 production targets, weighed down by outages and natural decline. Procurement teams have to support both stories together — with the same staff, the same budgets and the same supplier base.
Abadi LNG moves toward construction
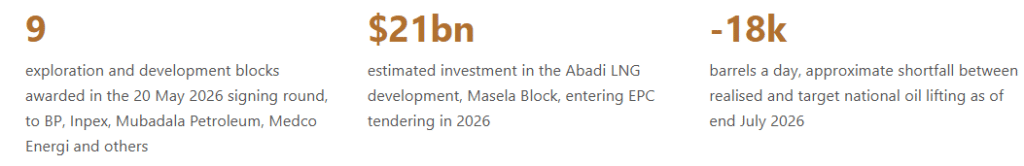
In February 2026, Inpex confirmed plans to open tendering for the Abadi LNG development in the Masela Block. The tendering covers engineering, procurement and construction — EPC, for short. The project is worth roughly US$21 billion and targets 9.5 million tonnes of LNG a year. Inpex is developing it with Pertamina and Petronas.
Front-end engineering design work began in August 2025. By early 2026, it had moved far enough for the government to call a “debottlenecking” session. Officials wanted to clear permitting obstacles before EPC tendering began.
Three months later, on 20 May, the energy ministry signed contracts for a new round of exploration blocks. BP, Inpex, Mubadala Petroleum and Medco Energi all gained new acreage — across West Papua, East Java, South Sumatra and offshore Aceh. The round forms part of a wider push to reopen basins that have sat undeveloped for years.
Production is missing its target
Indonesia’s oil lifting is not keeping pace with plans. On 26 August 2026, officials told a parliamentary hearing that national output had averaged 578,156 barrels a day through July. That is around five per cent short of the government’s 610,000 barrels-a-day target for the year.
Two flagship assets carried most of the blame. A gas pipeline leak at PT Transportasi Gas Indonesia disrupted supply to the Pertamina Hulu Rokan block early in the year. ExxonMobil’s Cepu block, meanwhile, continued a sharper-than-usual natural decline. Rokan’s output has fallen to around 133,000 barrels a day, down from roughly 151,000 a year earlier.
Together, these developments describe a supply chain now serving two pipelines at once: a capital-project pipeline and a maintenance-and-decline pipeline. Neither can wait for the other. That tension sets the context for the priorities below.
A two-track upstream landscape
The gap between target and actual production is not a rounding error. It runs close to 32,000 barrels a day, concentrated in two assets that together account for a large share of national output. The chart below sets out the headline numbers, given in testimony to Indonesia’s House of Representatives during 2026, alongside the exploration activity moving in the opposite direction.
2026 oil lifting: target against realised output (thousand barrels a day)
Sources: Ministry of Energy and Mineral Resources hearing with House of Representatives Commission XII, 26 August 2026 (national and Rokan figures); S&P Global CERA note of 25 August 2026 (Cepu peak and current range). Figures are approximate and rounded to the nearest thousand barrels a day.
Procurement teams now manage two very different jobs under one roof. One job is capital-project sourcing: long-lead equipment, EPC packages, specialist marine and subsea contractors. The other is operations-sustaining sourcing: spares, workover services, and power and gas-infrastructure repairs. Treating these as a single, undifferentiated pipeline is where several of the risks below begin.
Bring procurement into the project earlier
Some of the most important sourcing decisions on an upstream mega-project happen long before a tender goes out. Long-lead equipment, marine spread availability, inspection regimes and certification pathways all need lead time — sometimes years of it. Each depends on engineering decisions that procurement teams rarely see early enough.
Abadi LNG shows what “early” now has to mean. Front-end engineering design started in August 2025. By early 2026, the government was already convening cross-agency sessions to clear permitting and local-content obstacles, so that EPC tendering could proceed on schedule by mid-year. Teams placed contracts for project-management consultancy and engineering support alongside ongoing FEED packages — for the floating production, storage and offloading unit, subsea systems, export pipelines and the onshore LNG train. In practice, procurement, engineering and government permitting ran in parallel rather than in sequence.
For upstream operators more broadly, that points to three practical requirements. Procurement needs a seat inside FEED reviews, not just a role after contract award. Teams should run supplier-market assessment alongside concept selection, not after it. And long-lead item lists need regular updates against the evolving engineering baseline, rather than a fixed snapshot at sanction. EnergyEdge’s Engineering, Procurement & Construction Contracts (EPC) course works through exactly this interface between engineering decisions and procurement commitments.
Balancing TKDN commitments with supplier capability
Tingkat Komponen Dalam Negeri (TKDN) — Indonesia’s domestic component level requirement — remains a defining constraint on procurement design. In May 2026, an ESDM ministry official gave evidence to Commission XII of the House of Representatives. Upstream procurement had reached a cumulative domestic-content commitment of around US$1.5 billion as of April. That figure equals 62.95 per cent of a combined US$2.38 billion cost base for goods and services. Services procurement carried a much higher domestic component — 69.42 per cent — than goods procurement, at 45.74 per cent.
TKDN commitment by procurement category, as reported April 2026
Source: Directorate General of Oil and Gas, ESDM Ministry, presented to House of Representatives Commission XII, 21 May 2026 (as reported by ANTARA News). Figures reflect combined commitments for upstream oil and gas procurement as of April 2026.
Why services outperform goods
That gap between goods and services is structural, not incidental. Fabricated equipment, instrumentation and specialist materials often still rely on imported components or licensed designs. Inspection, logistics, catering, drilling and well services, by contrast, draw more easily on domestic firms.
The gap also creates a temptation. Contractors can meet aggregate TKDN targets by over-weighting services spend, rather than building real domestic manufacturing capability in goods categories. That approach satisfies a reporting requirement without closing the underlying capability gap.
Local content versus schedule
Abadi LNG shows this tension directly. As part of the debottlenecking effort, the government said it would consider relaxing certain domestic-content requirements — specifically to protect the project’s timetable. That is a clear signal: on the largest, most schedule-critical developments, a rigid content target can itself cause delay.
This does not weaken the case for local content. It does mean procurement teams need a documented, defensible basis for where domestic sourcing is realistic — and where it is not — rather than treating the percentage as fixed for every package.
None of this changes the basic sequence for any given package. Confirm technical specification first. Then check production or delivery capacity, quality systems, HSE performance and documentation. Only then should TKDN percentage decide between otherwise qualified bidders.
Vendor qualification across a widening operator group
The 20 May 2026 licensing round added more than acreage — it added new operating cultures. BP took interests in three blocks, including Bintuni and Drawa in West Papua, close to its existing Tangguh LNG infrastructure. BP also joined Inpex on the Barong block off East Java. Mubadala Petroleum secured the Southwest Andaman block offshore Aceh, which holds an estimated three trillion cubic feet of gas. Medco Energi added the Nawasena block in East Java. Each operator brings its own contracting standards, HSE expectations and vendor-approval process. The domestic supply base now has to satisfy all of them, often in parallel.
| Block | Location | Operator / consortium | Estimated resource |
|---|---|---|---|
| Bintuni & Drawa | Offshore West Papua | BP-led consortium | Gas, near Tangguh infrastructure |
| Barong | Offshore East Java | Inpex / BP | ~2.9 tcf gas |
| Southwest Andaman | Offshore Aceh | Mubadala Petroleum | ~3.0 tcf gas |
| Nawasena | East Java | Medco Energi | ~1.3 tcf gas |
| Gagah | Onshore South Sumatra | Proteknik Gagah Energi | ~173 mmbbl oil |
Selected blocks from Indonesia’s 20 May 2026 exploration contract signings, alongside the concurrent 2026 Indonesia Petroleum Bidding Round. Sources: S&P Global Commodity Insights and Reuters, 20–21 May 2026.
What operators are asking for
Established Indonesian suppliers face a genuine opportunity here — but only if they can prove consistent performance against varied, sometimes stricter, qualification frameworks. A vendor qualified for a Pertamina-operated block may still need to requalify for a BP or Mubadala scope, especially on documentation, sub-supplier control and quality assurance evidence. EnergyEdge’s E&P Technical Services Contract course covers exactly this shift, where a single services contract has to satisfy several operators’ standards rather than one. The eight-point structure below sets out the areas that recur across operator qualification processes, whichever company is asking the questions.
| Assessment area | What it establishes |
|---|---|
| Technical | Whether the supplier can meet the specification without deviation or exception |
| Capacity | Whether delivery is achievable within the project’s actual schedule, not the supplier’s stated lead time |
| Quality | Whether QA/QC systems and inspection regimes are adequate for the criticality of the item |
| HSE | Whether safety performance history supports the risk profile of the scope |
| Commercial | Whether the proposal is financially sustainable over the contract term |
| Delivery track record | Whether the supplier has a verifiable history of meeting lead times, not just quoting them |
| Sub-supplier control | How critical lower-tier suppliers are identified, monitored and substituted if they fail |
| Documentation | Whether certificates and project records will be delivered in the form the project actually requires |
Some qualification disputes turn on contract wording rather than technical fact — a deviation clause, a liability cap, an ambiguous acceptance test. That is a contract-drafting and risk-allocation problem as much as a procurement one. EnergyEdge’s Mastering Contract Law and Risk Mitigation in Energy course covers that territory directly.
Strategic sourcing over transactional purchasing
Not every category on an upstream programme carries the same risk. Treating them identically creates its own cost and schedule exposure. Strategic sourcing asks a different question than transactional purchasing. It is not simply what needs buying — it is how concentrated the supplier market is, where lead-time risk sits, and whether a category should go to package-by-package tender or a longer-term frame agreement.
Routine consumables and specialised drilling equipment are not the same category of risk. A sourcing strategy that treats them as though they were tends to under-manage the equipment that actually threatens the schedule.
Category management, supplier segmentation and portfolio tools such as the Kraljic matrix make that distinction explicit. They separate categories where several qualified suppliers compete on price from those where a small number of specialised vendors hold real leverage over schedule. EnergyEdge’s Purchasing & Procurement in the Upstream Oil & Gas Supply Chain course works through this segmentation directly, alongside frame agreements and market analysis. On a portfolio like Indonesia’s current pipeline — an LNG mega-project, new exploration wells, and sustaining work on mature fields, all running at once — that segmentation lets a procurement team apply competitive tendering where it is safe, and relationship-based, longer-term arrangements where supply concentration or technical risk makes annual re-tendering counter-productive.
Expediting, inspection and logistics do not end at contract signature
Placing an order is the easy part of procurement. What happens between award and delivery is where most schedule risk actually appears — and it rarely shows up in a supplier’s own status report.
Where delay typically enters a procured package
Common points at which reported status diverges from physical progress on upstream equipment packages.
Where delay hides
A vendor may report an item as “in production” while the engineering drawings underneath remain unapproved. Manufacturing can move ahead while inspection requirements are still under negotiation. Equipment can leave the factory on schedule and still arrive late, because nobody arranged the shipping documentation or inland transport in time. Effective expediting means tracking physical progress against these specific gates. It cannot rely on supplier-reported percentages alone.
Keeping pace with “Triple 100”
The scale of Indonesia’s current drilling programme makes this more than a theoretical risk. SKK Migas’s “Triple 100” programme targets 100 exploration wells and 100 multi-stage fracturing wells in 2026. An oilfield-services provider is supplying fracturing units under a supporting memorandum of understanding.
By February 2026, crews had drilled only 13 exploration wells and six fracturing wells against the approved work programme. That left the regulator needing 48 more exploration wells and 77 more fracturing wells by December, to hit the annual target. Programmes at this tempo need tender management, logistics and inspection capacity that can absorb repeated, closely spaced mobilisations — not just one-off campaigns.
Materials management under mature-field stress
Procurement’s job does not end when materials reach the warehouse. Someone still has to decide what to stock, how much, where, and when to replenish it. On Indonesia’s ageing producing base, that decision carries direct production consequences.
Rokan’s disruption, in numbers
The 2026 disruptions at Rokan make the point clearly. Output fell not because of a reservoir problem, but because a gas transmission pipeline leak — operated by a third party — cut supply to the field. The North Duri Cogeneration facility, which supplies the electricity that heavy-oil production at Rokan depends on, added its own operational problems on top.
Neither event is, strictly, a procurement failure. But the availability of spare parts, repair contractors and replacement capacity for this kind of infrastructure — pipelines, cogeneration plant, power systems — is a materials-management and critical-spares question. Mature-asset operators now face that test in real time. Cepu’s decline tells a similar story: even a well-run infill drilling campaign cannot fully offset the natural decline of a field that peaked at around 220,000 barrels a day in 2019–20 and has fallen ever since.
The stocking dilemma
The lesson for materials management is familiar from any mature-asset environment. Indonesia’s current output gap, though, leaves less room for error. Under-stock critical spares for power, gas-handling or artificial-lift equipment, and a routine maintenance event turns into a multi-week production loss. Over-stock them, and working capital sits idle — capital that could otherwise fund the drilling and workover activity the government is counting on to close the production gap.
Getting that balance right, field by field, is now a national-output question, not just a cost-control one. EnergyEdge’s Materials Management course focuses on exactly this trade-off, and its Lean & Sustainable Warehouse Management in Oil & Gas course covers the storage and handling side.
Data has to travel across a more fragmented network
People often frame digital procurement as a move from spreadsheets into software. Its real value, in the current environment, is narrower and more specific. It lets a procurement team answer, quickly: which purchase orders are behind schedule, which suppliers keep missing delivery milestones, and which categories are showing early signs of supply risk.
That capability matters more as the operator base widens. Regulators are already moving this way on the compliance side. SKK Migas increasingly monitors domestic-content reporting through a live database, rather than end-of-project reconciliation — turning TKDN tracking into a continuous activity rather than a closing task. The same logic applies more broadly to supplier and materials data. BP, Inpex, Mubadala, Medco and Pertamina entities now run qualification and expediting processes across overlapping supplier pools. Integrated visibility — shared where it makes commercial sense, and rigorous internally where it does not — lets problems surface while there is still time to act, rather than at the point a shipment fails to arrive. EnergyEdge’s Integrated Supply Chain Excellence in Oil & Gas course covers this ground end to end.
What this means going into 2027
SKK Migas projects 2027 oil lifting at roughly 602,000 to 615,000 barrels a day. That range sits close to the 2026 outlook of 600,000–610,000 barrels a day — itself dependent on closing the shortfall reported in August. The framing matters: the government is not projecting that new blocks and mega-projects will replace mature-asset performance any time soon. Abadi LNG will not ship its first cargo before the end of the decade at the earliest. The blocks awarded in May 2026 sit at the exploration and appraisal stage, not production. In the near term, closing Indonesia’s output gap depends mostly on the reliability of existing infrastructure — pipelines, power plants, well services — and on the pace of drilling programmes such as “Triple 100”.
For teams running oil and gas procurement in Indonesia, that argues against picking a single dominant priority. Early engagement on FEED and long-lead items still matters for the capital-project pipeline. TKDN compliance needs technical and commercial judgement, not just a percentage target — especially where schedule-critical projects ask for flexibility. Vendor qualification has to flex for a wider, more varied operator base without loosening technical or HSE standards. And materials management for power, gas-handling and artificial-lift equipment on mature fields now matters to national output as much as sourcing decisions on new developments. Over the next eighteen months, the organisations that manage this well will likely be the ones with real, integrated visibility across both pipelines — not the ones running capital-project procurement and operations-sustaining procurement as separate disciplines that just happen to share a budget line.
Frequently asked questions
Priorities and local content
Seven priorities stand out: early engagement on capital projects such as Abadi LNG; disciplined management of TKDN local-content commitments; vendor qualification across a wider operator base; strategic sourcing by category rather than uniform tendering; rigorous expediting and logistics after contract award; materials and critical-spares management for mature, gas- and power-dependent fields; and integrated digital visibility across procurement and supplier data.
Tingkat Komponen Dalam Negeri is Indonesia’s domestic component level requirement for goods and services procurement. As of April 2026, the ESDM Ministry reported a cumulative commitment of around US$1.5 billion — 62.95 per cent of a combined US$2.38 billion cost base. Services procurement, at 69.42 per cent, ran well ahead of goods procurement, at 45.74 per cent.
Operators, output and scope
The May 2026 licensing round brought BP, Inpex, Mubadala Petroleum and Medco Energi into new Indonesian acreage alongside Pertamina’s existing operations. Each operator applies its own standards for technical capability, quality systems, HSE performance and documentation. As a result, suppliers now have to satisfy several distinct frameworks, not just one.
A parliamentary hearing on 26 August 2026 reported national oil lifting at 578,156 barrels a day, against a 610,000 barrels-a-day target. A gas pipeline leak at the Rokan block and natural decline at the Cepu block drove most of that gap. In both cases, the shortfall turns on the availability of power, gas-handling and well-service equipment and spares — placing materials management and supplier readiness alongside drilling activity as levers for closing the gap.
Procurement covers sourcing and contract award. Supply chain management, however, goes further — into expediting, inspection, transportation, inventory and warehouse management, and supplier performance management. These disciplines decide whether an awarded contract actually turns into equipment and services on site, on time.
